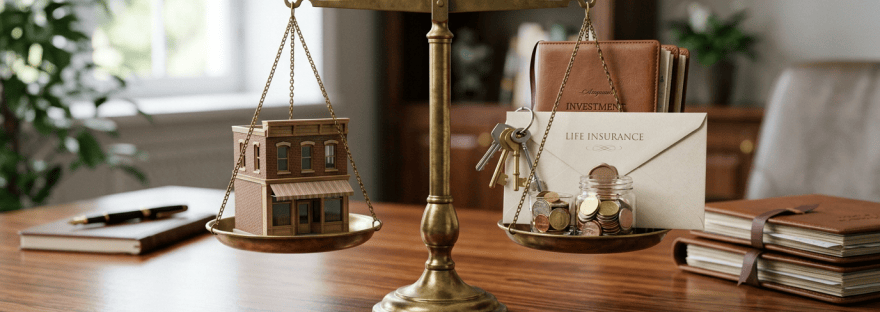
For parents who own a family business, estate planning can present a difficult question: How do you treat your children fairly when only one of them will inherit the company?
Dividing everything equally may seem like the simplest solution. However, giving each child an equal share of the business can create practical and emotional challenges—especially when only one child works in the company or is prepared to lead it.
Fair does not always have to mean equal. The goal is to create a plan that recognizes each child’s circumstances while protecting the future of the business and preserving family relationships.
Why Equal Ownership May Not Be the Best Solution
Suppose one child has worked in the family business for many years, helped increase its value, and expects to assume responsibility for employees, customers, and daily operations. The other children have pursued separate careers and have little involvement with the company.
Leaving equal ownership to all of the children may create several problems:
- The child running the company may lack sufficient decision-making authority.
- Children who do not work in the business may expect regular distributions.
- Disagreements may arise over salaries, reinvestment, expansion, or the sale of the company.
- The active child may believe that years of work and sacrifice were not recognized.
- The other children may feel excluded from a valuable family asset.
These tensions can affect both the company and the family. A structure that looks equal on paper may not feel fair in practice.
Separate Business Leadership From Family Inheritance
The first step is to distinguish between who is qualified to lead the business and how the overall estate will be distributed.
The child who is prepared to run the company may need voting control or full ownership to make timely decisions. The other children can potentially receive different assets, financial benefits, or nonvoting interests without participating in daily management.
This approach allows the business to remain operational while still considering the needs of every child.
Consider Equalizing the Inheritance With Other Assets
One possible strategy is to leave the business to the active child and provide other assets to the remaining children. These assets might include:
- Retirement or investment accounts
- Real estate
- Cash and savings
- Life insurance proceeds
- Other business interests
- Personal property
Perfect mathematical equality may not be possible or necessary. Asset values can change, and the child receiving the company is also accepting the risks and responsibilities of business ownership.
Parents should consider both the current value of each asset and its future characteristics. A business may have significant potential value but limited liquidity, while an investment account or insurance benefit may be immediately accessible.
Use Life Insurance to Provide Liquidity
Life insurance is sometimes used to help balance an estate when most of the family’s wealth is tied to a business.
For example, the business may pass to the child involved in the company, while life insurance benefits are directed to the other children. This can provide funds without forcing the active child to sell the business or borrow heavily to pay siblings.
The appropriate amount and ownership structure will depend on the family’s circumstances. Insurance coverage and beneficiary designations should be reviewed regularly with qualified financial, insurance, legal, and tax professionals.
Consider a Purchase Instead of an Inheritance
The active child might purchase some or all of the business rather than receiving it as an inheritance. The sale could occur gradually or through an installment arrangement.
The proceeds may provide retirement income for the parents or eventually become part of the estate available to all children. A purchase can also reinforce that business ownership carries a financial obligation rather than being an automatic family entitlement.
However, the arrangement must be affordable for the successor and financially appropriate for the parents. An independent valuation can help establish a supportable purchase price.
Recognize the Active Child’s Contributions
A child who works in the business may have contributed to its growth over many years. Parents should consider whether that child received market-rate compensation during that time.
If the child accepted lower pay with the expectation of eventually receiving ownership, that understanding should be addressed clearly and documented. Informal promises can create significant conflict if family members remember them differently.
Compensation for current work and the future transfer of ownership should be treated as related but separate planning decisions.
Decide Whether Nonvoting Ownership Is Appropriate
In some situations, parents may want all children to benefit financially from the business while giving control to the child who operates it. This might involve voting and nonvoting ownership interests.
The active child could hold voting control, while siblings receive nonvoting interests that may entitle them to a share of distributions or future sale proceeds.
This structure is not appropriate for every family. Siblings may still disagree about compensation, distributions, or whether the company should be sold. A carefully drafted ownership agreement should address decision-making authority, transfers of ownership, valuation, distributions, and dispute resolution.
Explain the Reasoning Behind the Plan
Surprises can create resentment. When appropriate, parents should explain the succession and estate plan while they are able to answer questions.
The conversation should focus on the reasoning behind the decisions—not merely the dollar value assigned to each child. Parents can explain that the active child will receive the responsibility and risk associated with the company, while the other children will receive assets that do not require them to participate in the business.
These discussions may be uncomfortable, but they provide an opportunity to correct misunderstandings and manage expectations.
Put Agreements in Writing
Verbal understandings are not enough. Business succession and estate-planning decisions should be reflected consistently across all relevant documents.
These may include:
- Wills and trusts
- Buy-sell agreements
- Operating or shareholder agreements
- Employment and compensation arrangements
- Life insurance policies
- Beneficiary designations
- Powers of attorney
- Business-continuity instructions
Documents should be reviewed regularly to make sure they continue to reflect the family’s wishes and current circumstances.
Work With a Coordinated Advisory Team
Balancing a family business and an estate may involve financial, legal, tax, insurance, and valuation considerations. Decisions made in one area can have unintended consequences in another.
A coordinated team may include a financial advisor, estate-planning attorney, accountant, insurance professional, and business-valuation specialist. In families with complicated relationships, a family-business consultant or facilitator may also be helpful.
Fairness Is Personal
There is no formula that makes every family-business inheritance fair. Each child may have different responsibilities, needs, abilities, and relationships with the company.
The most effective plans consider more than equal dollar amounts. They seek to protect the business, recognize individual contributions, support the parents’ financial needs, and preserve family relationships.
Starting early gives families time to explore their options, communicate openly, and develop a plan that reflects both their financial priorities and personal values.
This material is provided for general informational purposes and is not intended as legal, tax, accounting, insurance, or investment advice. Business owners should consult the appropriate professionals regarding their individual circumstances.
Discover more from FPA Owner Transitions
Subscribe to get the latest posts sent to your email.


